Industry News
.png)
When normal becomes the risk
For an industry that has spent much of the 2020s making extraordinary money from things going wrong, this week brought an unfamiliar threat: things starting to go right.
Some of shipping’s most important pressure points showed signs of easing. At the Panama Canal, for instance, improving rainfall allowed the authorities to announce this week an increase in drafts and more daily transit capacity from October 15.
Half a world away, the return to Suez is gathering momentum. The Premier Alliance will send its FE1 Asia-Europe service back through the canal this month, joining Maersk, Hapag-Lloyd, MSC and others in gradually abandoning Cape of Good Hope diversions. More than 140 containerships representing over 2m teu have returned to Suez routings since May.
Normality is relative. Merchant ships are still queuing for EU naval escorts through the southern Red Sea, with Brussels admitting it lacks sufficient warships to satisfy demand.
The same tentative recovery is evident at Hormuz despite a host of attacks in recent days. Middle Eastern crude exports rebounded sharply in September and traffic through the strait has recovered dramatically from July’s lows.
Even Washington and Beijing managed a temporary outbreak of cooperation. Presidents Xi Jinping and Donald Trump extended the suspension of reciprocal port fees until January and agreed new commodity trade commitments, providing shipping with some breathing space from a dispute that had briefly turned vessels themselves into weapons of trade policy.
All of which raises an awkward question for shipowners: what happens when the disruptions that created so much effective vessel demand begin to disappear? For now, absolutely nothing resembling a correction.
The ClarkSea Index reached another all-time high of $66,421 a day last Friday, while VLCCs remain in another universe. More extraordinarily, a five-year-old VLCC is now valued at $207.6m, 49% more than a newbuilding, while even a 15-year-old ship has crossed newbuild parity for the first time. Splash compared the tanker market today with climbers entering Everest’s death zone: spectacular altitude, but historically not somewhere markets remain for long.
Dry bulk, meanwhile, is beginning to tell a slightly different story. First-half tonne-mile demand increased 6.7%, more than twice the growth in actual cargo volumes, while the actively trading fleet expanded just 3.2%. Guinea, Simandou and changing commodity sourcing are providing longer-haul demand that looks less dependent on any single crisis.
That divergence sits at the heart of this week’s Maritime CEO interview with Norden chief executive Jan Rindbo. Norden is reducing tanker exposure and directing more capital towards dry cargo, where Rindbo sees a better risk-reward balance. His warning for the wider industry is a familiar one: do not chase yesterday’s earnings with investments made near the top of a cycle.
Ashore, APM Terminals chief executive Keith Svendsen supplied an equally useful dose of discipline in this week’s Splash Ports CEO interview. Rather than automatically building more, Svendsen wants terminals to extract far more from what they already own. APM Terminals’ Gemini hubs are handling over 70% more moves per hour than a decade ago. “Without operational discipline, you simply buy a larger version of the same problem,” he told Splash Ports.
Over at SplashTech, meanwhile, this week’s lead feature looked at why fatigue, weak access discipline, blurred IT/OT accountability and poor onboard processes still leave vessels exposed in ways software alone cannot solve.
AI was the theme that dominated much of discussion at last week’s Splash Singapore. For those unable to attend the event, this week’s Splash Wrap podcast, carried below, identifies the key themes surrounding AI and shipping from Asia’s leading shipowner conference.
Read more: https://splash247.com/splash-wrap-when-normal-becomes-the-risk/
RELATED STORIES
.jpg)
What Is El Niño, and What Does It Mean for Weather, Water, and the Global Economy?
El Niño looks to reach an intensity unpr...
Know More.png)
.png)
The Strait of Hormuz Crisis Is Repricing Freight, Not Just Oil
On September 12, an unidentified vessel was str...
Know More.jpg)
.jpg)
Middle East shipping squeezed as Hormuz and Bab el-Mandeb risks converge
Middle Eastern shipp...
Know More.jpg)
.jpg)
.jpg)
Global trade faces softer demand, tighter capacity
Global manufacturing activity recorded its 12th...
Know More.jpg)
.jpg)
Historic Drought Leaves Europe's Supply Chains High and Dry
As Europe deals with the fallout of record summ...
Know More.jpg)
.jpg)
.jpg)
.jpg)
Global Ship Orderbook Growth Hits Fastest Pace Since Pre-Lehman Boom
At 27% year-on-year,...
Know More.jpg)
Chinese Shipper Launches First Cargo Service Through Arctic
Chinese shipper Sea Legend is starting the...
Know More.jpg)
Reactive Supply Chain Strategies Are No Match for Disruption
Extreme weather events, labor shortages, intern...
Know More.jpg)
.jpg)
.jpg)
.jpg)
Water Levels Along Rhine, Danube Rivers Sink to Record Lows
Europe's Rhine River has fallen to record low l...
Know More
The Data Center Boom Has a Component Problem
Strip away the ribbon cuttings and the renderin...
Know More.jpg)
The importance of insurance during the supply chain cannot be ignored.
For decades, cargo criminals followed a familia...
Know More.jpg)
Iran Demands Crew, Cargo Details to Allow Ships Through Hormuz - SupplyChainBrain
Vessels seeking to transit the Strait of Hormuz...
Know More
Iran War Threatens Global Food Supply Chains - SupplyChainBrain
While the Iran war's impact on oil prices has c...
Know More
Maersk Adjusts Emergency Contingency Surcharges Amid Regional Disruptions - SeasNews
Maersk has announced adjustments to its Emergen...
Know More
Container rates climb after weeks of decline - Shipping Watch
The price of container freight from Shanghai to...
Know More
Trump’s Maritime Golden Age could prove costly for shipping - Seatrade-Maritime
With the USTR fees on Chinese built and owned v...
Know More
Yard Bottlenecks Ripple Through Supply Chains in 2026 - SupplyChainBrain
Once an afterthought in supply chain strategy, ...
Know More
MENA set to lead global sustainable aviation fuel market - Technical Review Middle East
The Middle East and North Africa (MENA) region ...
Know More
The New Economics of Warehousing: Flexibility Over Footprint - SupplyChainBrain
The warehousing landscape is undergoing a quiet...
Know More
Retail giants back first e-ammonia boxship - splash247
The Zero Emission Maritime Buyers Alliance (ZEM...
Know More
Shipping lines gear up for post-Red Sea crisis restructure - SeaTrade Maritime
Seatrade Maritime News and MDS Transmodal exami...
Know More
What Peak Season 2024 Taught Us About the New Rules of Holiday Shipping - SupplyChainBrain
Last year’s peak season proved what many ...
Know More
Welcome to the age of uncertainty - splash247
The opening Big Issues session of the Maritime ...
Know More
Jebel Ali Port breaks nine-year record for container volume in July on Cepa deals - The National News
DP World’s Jebel Ali Port has reported it...
Know More
Box rates rates sink to lowest levels since Red Sea crisis - Splash247
Container freight rates are sliding further, wi...
Know More
UN: Trade reset, geopolitics to hurt container trade growth - FreightWaves
Maritime trade is entering a period of fragile ...
Know More
Carriers reroute fleets to sidestep US levy - splash247
Global shipping is realigning fleets in anticip...
Know More
EU Takes Aim at Shein and Temu Over Flood of Unsafe Products - SupplyChainBrain
EU Justice Commissioner Michael McGrath is vowi...
Know More
Second half air cargo volumes depend on market diversification - Air Cargo News
Air cargo demand growth is present outside of t...
Know More
Up to Dhs500,000 fine for firms circumventing Emiratisation targets: Ministry - gulftoday.ae
The Ministry of Human Resources and Emiratisati...
Know More
Shipping in wait-and-see mode as Iran and Israel conflict continues - lloydslist.com
TANKER rates remain elevated, along with the fo...
Know More
Container freight rates fall but Red Sea return will be tipping point - seatrade-maritime.com
The Drewry World Container Index (WCI) shed a f...
Know More
AD Ports Group Opens First Inland Dry Port Facility in Abu Dhabi - transportandlogisticsme.com
AD Ports Group has announced the inaugu...
Know More
Carriers cautious on return to Red Sea as Houthis say they will end attacks - FreightWaves.com
Yemen’s Houthi rebels said they will ceas...
Know More
Have carriers failed to adjust to a new normal? - Seatrade-Maritime
Liner shipping operators are failing to act on ...
Know More
Shippers warned to ensure contingency plans are in place ahead of a potential strike at US East Coast and Gulf Coast ports next week - Container News
Transportation and logistics providers, port op...
Know More
Ships Fleeing the Red Sea Now Face Perilous African Weather - SupplyChainBrain
Ships sailing around the southern tip of Africa...
Know More
The U.S.-China Trade War Heats Up, And Businesses Move to Adjust - -SupplyChainBrain
The “quiet” trade war that has been...
Know More
More ships and more containers needed for 'feverish' box shipping sector - The Loadstar
Supply in container shipping has become “...
Know More
Ocean and airfreight rate differential narrows - Air Cargo News
The difference between ocean and airfreight rat...
Know More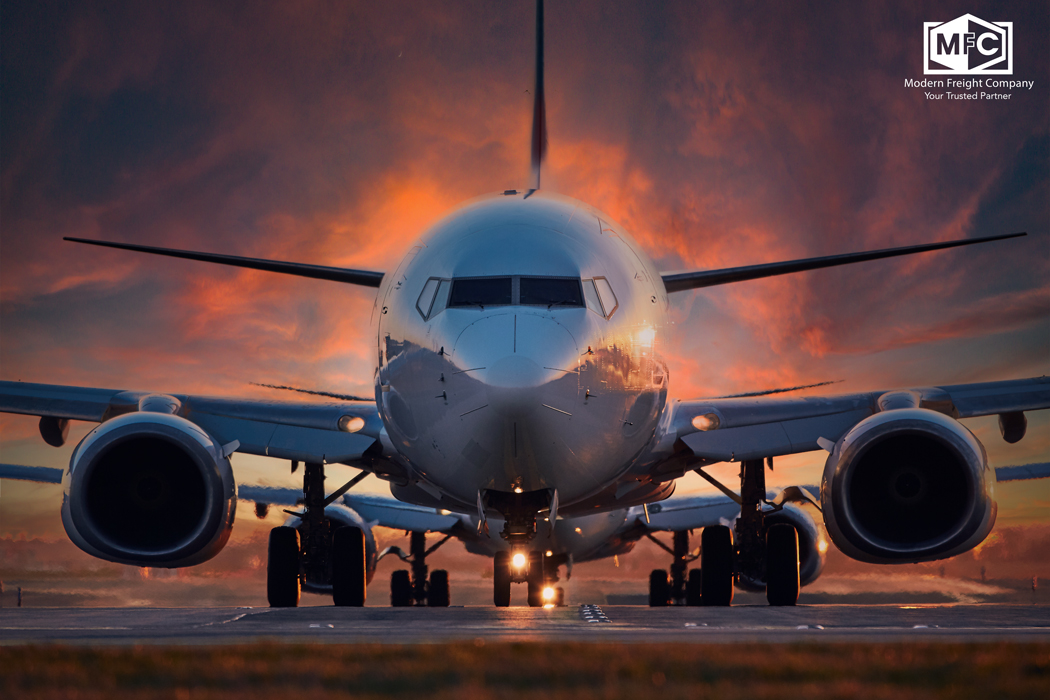
US Demand For Goods From 2 Chinese Firms Sends Air Cargo Rates Soaring - NDTV
Two Chinese companies have turned the global ai...
Know More
Mounting container shortages creating 'total havoc' - The Loadstar
Containers out of northern China are becoming i...
Know More
11,100 new slots a day: April smashes records for liner deliveries - Splash247
The teu tsunami coming out of Asian yards shows...
Know More
Mixed signals on container freight rates as Red Sea alarm subsides - Seatrade Maritime
Linerlytica, however, reported this week that &...
Know More
Jebel Ali returns to top-10 busiest container ports - Container News
Alphaliner's report said the Middle East’...
Know More
The Evolution of Physical Security Technology in the Supply Chain Industry - SupplyChainBrain
The seamless operation of supply chains, which ...
Know More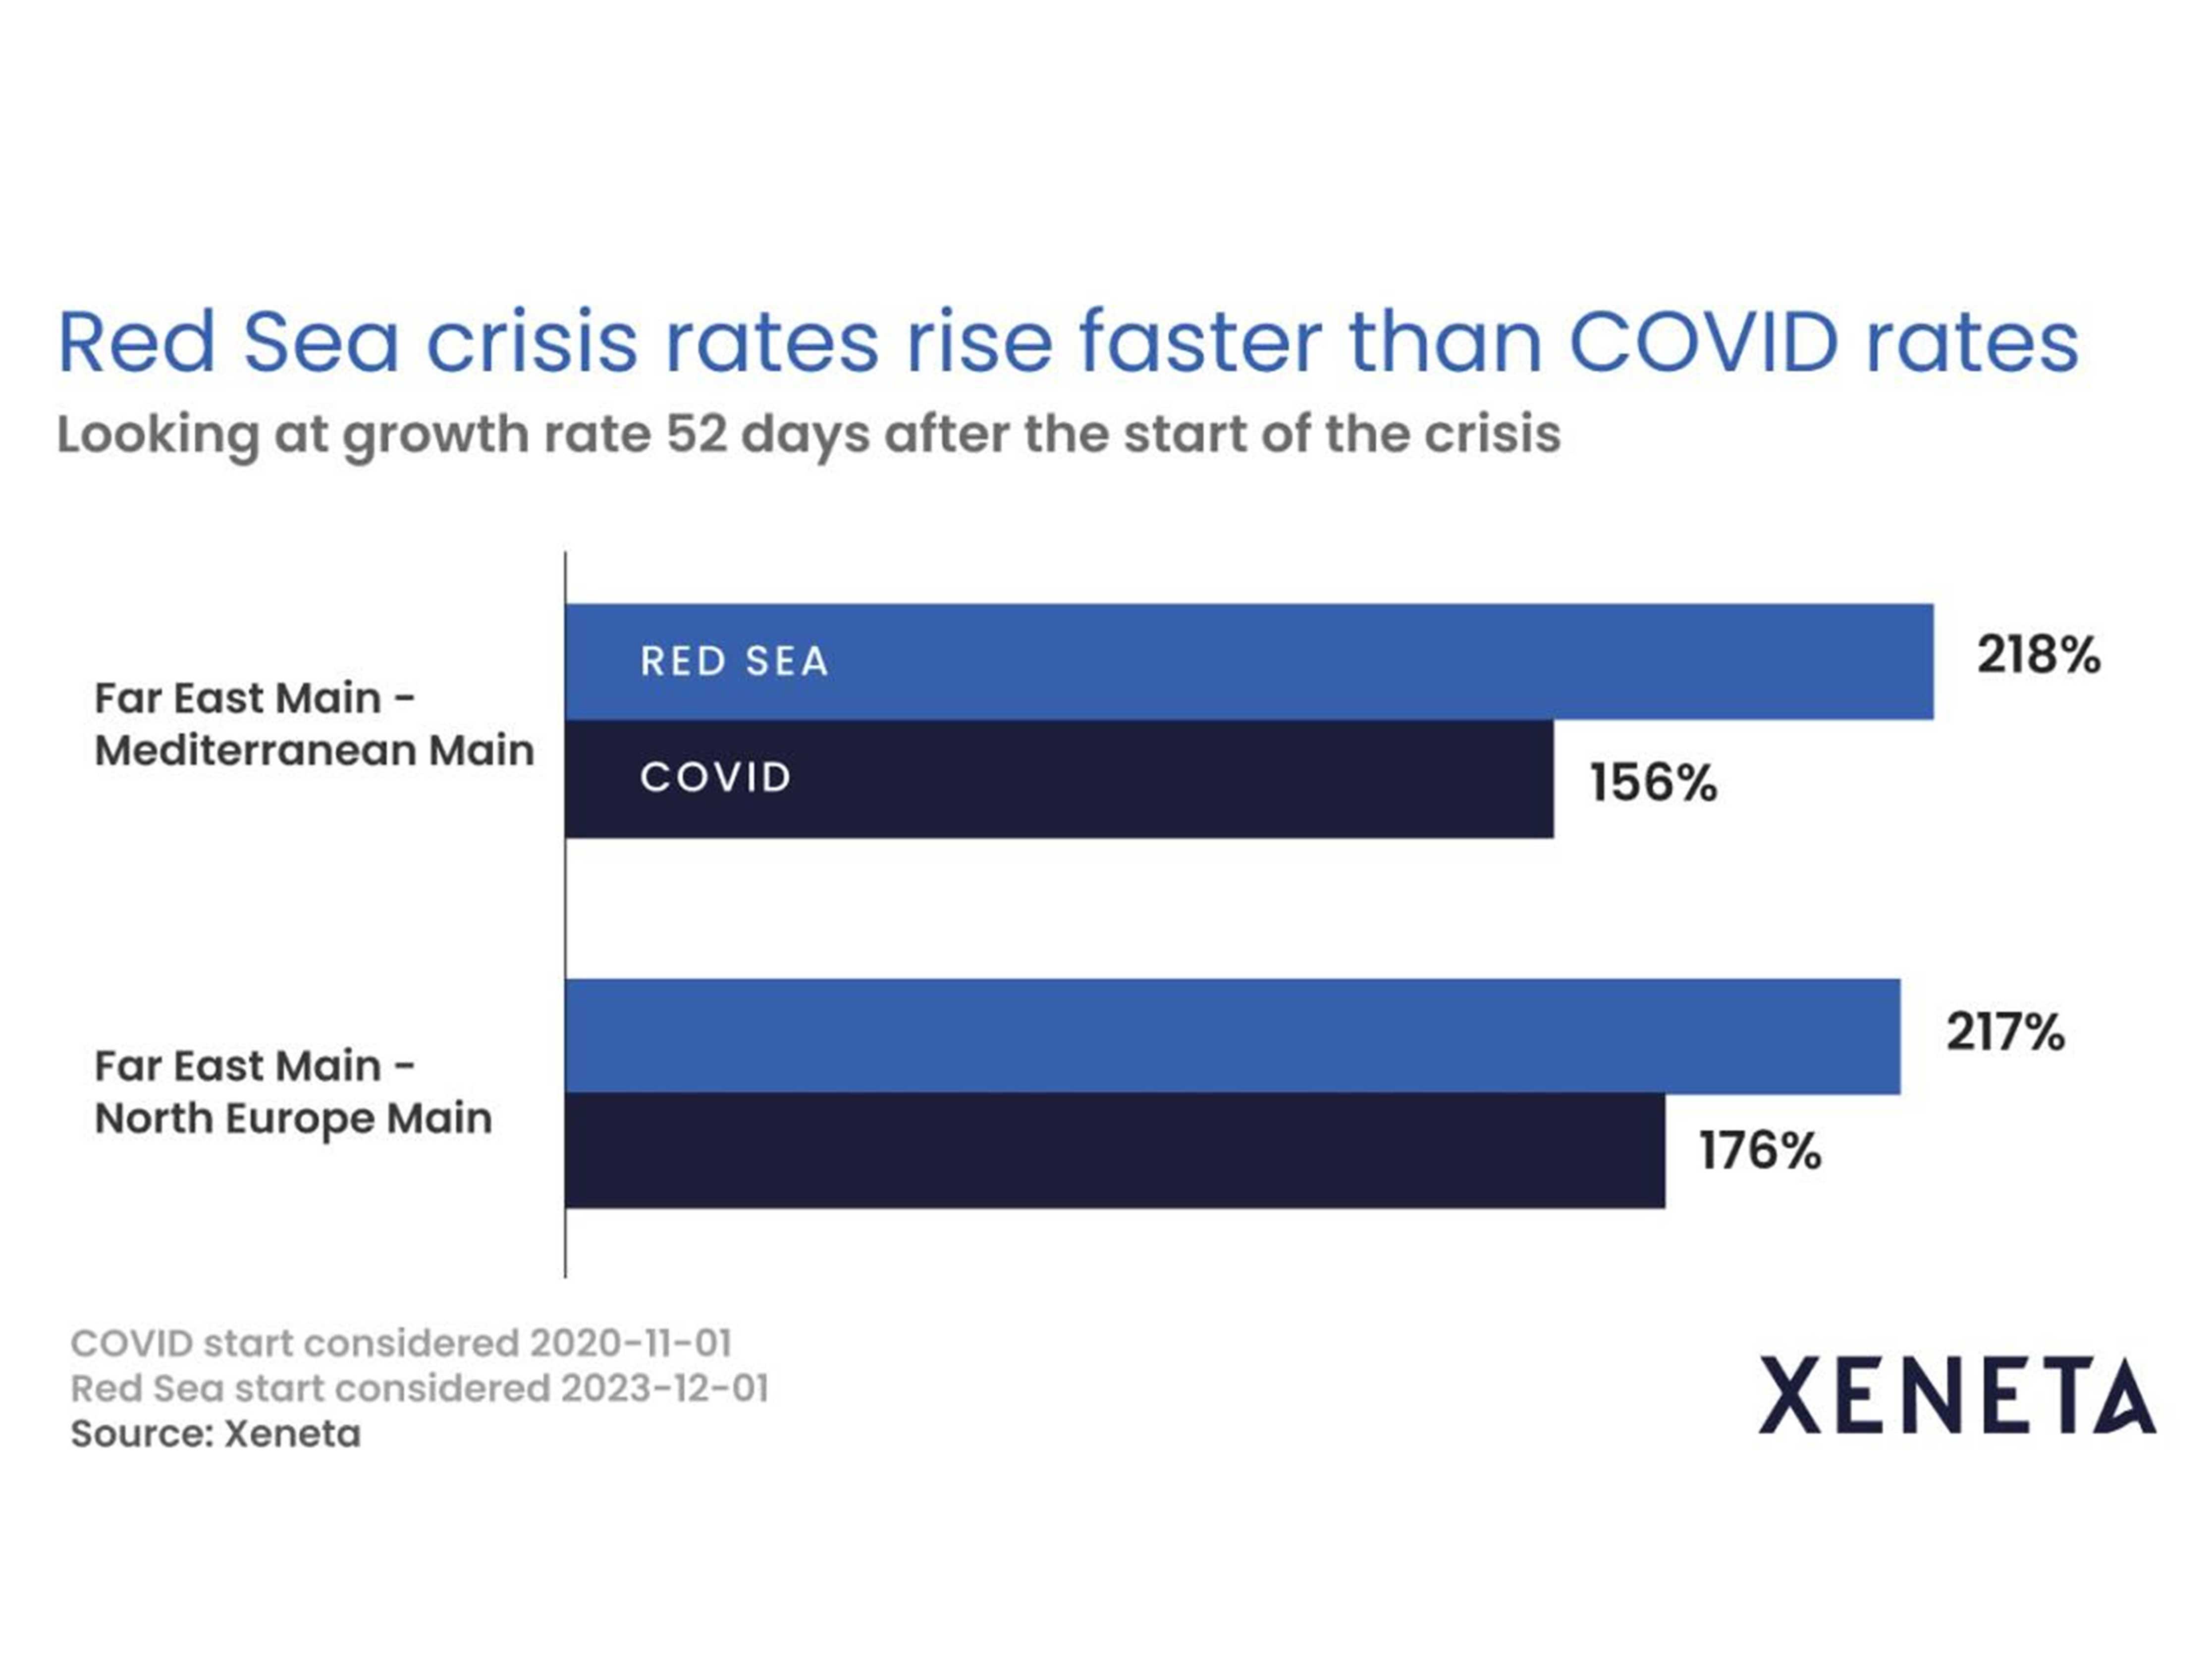
Red Sea crisis impact on box rates more rapid than Covid-19 - Asean Lines
The Red Sea crisis has seen ocean freight rates...
Know More
Freight crime on the up as gangs become more tech-savvy - The Loadstar
Internet-enabled crime and insider involvement ...
Know More
High demand, low supply: Dubai faces warehouse shortage amid new business influx - Logistics Middle East
Dubai is facing a shortage of warehouse space, ...
Know More
VGM container weight mis-declaration 'rampant at most ports', say forwarders - The Loadstar
Container carriers are dealing with widespread ...
Know More
CMA CGM announces overweight surcharge from Middle East Gulf to Europe and Mediterrannean - Container News
CMA CGM announced it will implement a new overw...
Know More
Bleak outlook for box trades as demand weakens prior to Golden Week - The Loadstar
Export bookings leading up to China’s Gol...
Know More
Ship queue grows at both ends of Panama Canal and congestion builds - The Loadstar
Draught limits on vessels seeking passage throu...
Know More
Over 60% of Logistics Companies Are Investing in Supply Chain Management Systems-SupplyChainBrain
Almost two-thirds of logistics companies (64%) ...
Know More
Growing India-UAE trade flows to benefit from domestic currency invoicing - The Loadstar
After a free trade deal last year, India and th...
Know More
Air cargo market still weakening while players search for optimism - The Loadstar
News that airlines are starting to park some fr...
Know More
Box rates to Gulf and S America rise as Asia-Europe/US prices falter - The Loadstar
Container freight rates from China to ’em...
Know More
Up to Dh5,000 fine for owners of some vehicles who fail to register in tracking system before October 30 - Khaleej Times
The Federal Authority for Identity, Citizenship...
Know More
Plot a (positive) course for air freight rates...if you dare - The Loadstar
Amidst the economic doom and gloom, with claims...
Know More
Imports Continue Slow Climb Despite Cuts in 2023 Forecast - The Maritime Executive
The Global Port Tracker has not yet forecast th...
Know More
Some ocean trades stabilising, but transatlantic rates still falling - The Loadstar
Container spot rates from North Europe to the U...
Know More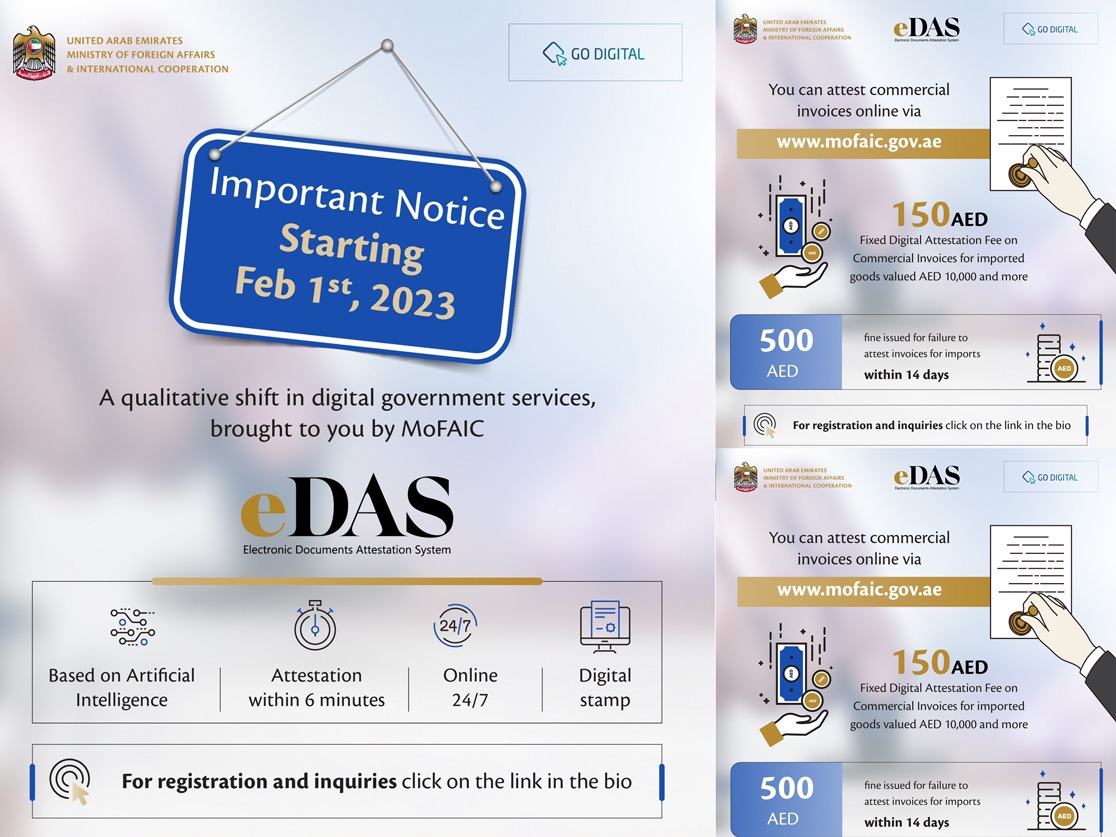
UAE announces fees on international imports in 2023 - Arabian News
The UAE is set to introduce new import rules, s...
Know More
China's Lockdowns are Over, but its Shipping Outlook is Still Mixed- The Maritime Executive
Beijing’s on-and-off COVID lockdowns crea...
Know More
Ocean carriers plan to blank half their sailings from Asia, post-CNY - The Loadstar
Against a background of extremely weak demand f...
Know More
Airfreight loses as shippers switch to cheaper ocean routes to save costs - The Loadstar
Shippers are merrily switching modes, back to s...
Know More
Protests at China lockdowns spread, with supply chains looking vulnerable again - The Loadstar
Anti-lockdown protests have broken out across m...
Know More
Air cargo peak season evaporates on low demand, higher capacity
It’s the time of year when retailers typi...
Know More
Black Sea ro-ro operations adapt to the new normal as companies seek opportunities - The Load Star
War in Ukraine has forced the re-routing of car...
Know More
Port of Felixstowe strike could see air cargo demand rise further: Air Cargo News
Strike action at the UK’s biggest contain...
Know More
Why container ships probably won't get bigger: BBC
When the Ever Ace, one of the largest container...
Know More
Consumers Prefer Personal Touch, Predictability, Over Super-Fast Delivery
To successfully ride the bucking growth of e-co...
Know More
Air freight 'turned upside down' as capacity slumps and rates climb
Air freight capacity has indeed shrunk, accordi...
Know More
Robotics in Warehouses- Enabling smarter and more cost-efficient logistics
Warehouses are the heart of supply chains and a...
Know More
DP World reports strong volume growth of 17.1% in 2Q 2021
DP World Limited handled 19.7 million TEU (twen...
Know More
Maersk to redesign its ocean network in West & Central Asia
Maersk is redesigning its ocean network in West...
Know More
DP World acquiring Imperial Logistics for $890m expanding Africa footprint
DP World has announced an offer to acquire Sout...
Know More
Secondhand Containership Market Heats up in 2021 driven by demand
Skyrocketing container shipping freight rates a...
Know More
DP World acquires leading US-based supply chain solutions provider - GCC Ports
DP World announces the acquisition of 100 per c...
Know More
Hapag-Lloyd and ONE join Maersk’s blockchain platform
Two of the largest container carriers in the wo...
Know More
Hapag-Lloyd to provide full transparency on vessel arrivals.
With this initiative on schedule reliability, H...
Know More
Just when you think shipping costs can’t go higher, increasing fuel cost are going to push prices up for shippers.
The price of Brent crude topped $72 per barrel ...
Know More
Port of Shenzhen faces severe congestion: container-news.com
The congestion at the Port of Shenzhen, China, ...
Know More
Hapag-Lloyd further expands its container fleet: 60,000 TEU of standard containers ordered- gccports.com
The sharp increase in demand has led to a short...
Know More
Globally, container manufacturing is controlled by three companies. Here is an insight into how this is impacting the global supply chain.
Never before has the humble ocean shipping cont...
Know More
UAE to allow investors full ownership of companies from June 1 - Khaleej Times
The landmark reform was originally slated to ro...
Know More
Logistics Passport: A game-changer for Dubai trade.
The WLP will be playing an instrumental role in...
Know More
Desperate shippers swallow contract rates at double 2020 Levels - container-news.com
Early indications from the annual contract nego...
Know More
Volatility in the shipping market likely to continue till Q4 - Sea Trade Maritime News
In a trading update for Q1 2021 Maersk signific...
Know More
UAE economy performs better than expected, on track towards recovery in 2021 - Khaleej Times
The UAE economy performed better than expected ...
Know More
2020 – A year of remarkable turnaround for container shipping
Due to the change in shopper behavior during th...
Know More
2021 Trends In Retail Automation And Store Supply Chains
Some container vessels have been sailing from A...
Know More
Container shortages the biggest disrupter: where are all the empty boxes?
Some container vessels have been sailing from A...
Know More